Monday, February 24, 2014

Two Out of Three

The following are ideas from the book "Profiting with Iron Condor Options", by Michael Benlifa.  I am summarizing the idea and trying to put in into practice in my Trading Plan.  Most of the time you cannot get the perfect trade three out of three considerations below.  You got to choose just two out of three.  Which two?

The three considerations when selling Iron Condors are :
  1. Position : Delta 10s, outside previous highs and lows
  2. Price: Credit of 20% of margin
  3. Time : Expiration is in 4 to 5 weeks
Michael suggest the first two : Position and Price, leaving Time negotiable.


Thursday, February 20, 2014

N225 Index Option Review

After decided not to trade HSI Index Option, I continue to explore another market/product for Option trading, the Nikkei 225.

Option Spec: (http://www.ose.or.jp/e/derivative/225options)

  • Exercise Style : European
  • Contract unit : JPY 1,000 per index point
  • Minimum Spread : 125 point, ie JPY 125,000 (~USD 1221.42)
  • Trading Hours : 9:00-15:15, 16:30-3:00 (Japan Hours)
Cost of Trading
1. Market Data JPY 200.00 (~USD 1.95)
- Osaka Sec Exch JPY 200.00

N225 Market Data cost is ok.  Not too high.  About on par with US Options.  For example, Korea is free, Singapore is SGD 1.00 (~USD0.78) and US Bundle (USD 10.00)  & US Options (USD 1.50) are waived when monthly commission generated reached USD 30.00 & USD 20.00 respectively.

2. Commission
- N225 commission is also not bad.
- 0.18% of option value, min JPY 100 (~USD 0.98) per order
- 0.2% of option value, min KRW 1,000 (~USD 0.93) per order

For a 10% premium collected from Credit Spread,
- N225 commission will take 1% away from the 10% premium received, ie for every $100 premium received, $1 will be deducted for commission.
- K200 commission will only take about 0.76% (depending on contract value) from the premium, ie for every $100 premium received, only about $0.76 is deducted for commission.

3. Margin
- N225 margin is good
- for a N225 Option 125pt Spread (min spread), the Initial & Maintenance margin is about USD 463 & USD 370 respectively
- for a K200 Option 2.5pt Spread (min spread), the Initial & Maintenance margin is about USD 637 & USD 510 respectively

For N225 Option, selling a 125pt Spread to receive say 15 pt (cannot do 12.5 pt. so, 12% premium) is about JPY 15,000 (~USD 146.57), I will need to tied up USD 463/370 initial/maintenance margin.  Return On Margin (ROM) is 31.65%/39.61%.

For K200 Option, selling a 2.5pt Spread to receive say 0.3 pt (adjust to 12% premium as N225) is about KRW 150,000 (~USD 139.90), I will need to tie up USD 637/510 initial/maintenance margin.  Return On Margin (ROM) is 21.96%/27.43%.

4. Option price spread and volume
As with K200, the bid/ask spead is very close, mostly 1-2 ticks wide.  Bid and Ask volume is also good.


Risk/Reward
1. Spread Risk
- min spread is 125 points, which equate to JPY JPY 125,000 (~USD 1221.42) 
- K200 min spead is 2.5 points, which equate to KRW 1,250,000 (~USD 1,165.39)
- this is about the same

2.  Support & Resistance
- as my selection of Strike is primary base on Support & Resistance (that may change), the validity of Support & Resistance is important
- N225 is in general similar to K200, with enough up & down (volatility) but at the same with good support & resistance.


3. Number of Strikes
One problem I have with K200 is the number of Strikes.  It is quite limited.  It is about 26 strike prices(current month) and 18 strike prices (next month).  This make adjustment kind of challenging at times.
N225 does not has this problem.  It has abundant of Strikes to trade.

4. Trading Hours
N225 Trading hours coincide with K200 for T-session (regular trading hours), where the Index is moving.  However, N225 has a T+1 session (non-regular trading hours) that you can continue to trade, even though spread and volume is not as good as T-session. 


Conclusion
N225 Option in many ways are comparable as K200, and better in some areas.  As such, I will be trading N225 in addition to K200.


Karen SuperTrader, February 11, 2014

There is a recent interview with Karen, the SuperTrader on February 11, 2014 on tastytrade.  I cannot find the YouTube version for this recent interview.  You can view the interview at tastytrade.  Need a account to login though.

https://www.tastytrade.com/tt/shows/tasty-extras/episodes/9236

Friday, January 24, 2014

HSI Index Option Review

I want to trade another market/product in addition to K200 Index Option to diversify.  With that, I start to explore Hong Kong Hang Seng Index Option.

Basic Option Spec: (http://www.hkex.com.hk/eng/prod/drprod/hkifo/options.htm)

  • Exercise Style : European
  • HSI Option is HKD 50 per index point
  • Minimum Spread : 200 point, ie HKD 10,000 (~USD  1,288.94)
  • Trading Hours is 9:15m - 12:00noon & 1:00pm - 4.15pm


Cost of Trading
1. Market Data HKD 40.00 HKD (~USD 5.16)
- Hang Seng Indices HKD 15.00
- HKFE Deriv HKD 25.00
- Korean Stk Exch Deriv Free

IB market data is generally cheap.  While USD 5.16 market data per month is not expensive, it is relative more expensive than other exchanges.  For example, Korea is free, Singapore is SGD 1.00 (~USD0.78) and US Bundle (USD 10.00)  & US Options (USD 1.50) are waived when monthly commission generated reached USD 30.00 & USD 20.00 respectively.

2. Commission
- HKD 30.00 (~USD3.86) per contract
- 0.2% of option value, min KRW 1,000 (~USD 0.93) per order

For a 10% premium collected from Credit Spread,
- HSI commission will take 6% away from the 10% premium received, ie for every $100 premium received, $6 will be deducted for commission.
- K200 commission will only take about 0.76% (depending on contract value) from the premium, ie for every $100 premium received, only about $0.76 is deducted for commission.

3. Margin
- for a HSI Option 200pt Spread (min spread), the Initial & Maintenance margin is about USD 1,201 & USD 961 respectively
- for a K200 Option 2.5pt Spread (min spread), the Initial & Maintenance margin is about USD 637 & USD 510 respectively

For HSI Option, selling a 200pt Spread to receive say 20 pt (10% min premium) is about HKD 1,000 (~USD 128.81), I will need to tied up USD 1,201/961 initial/maintenance margin.  Return On Margin (ROM) is 10.72%/13.40%.

For K200 Option, selling a 2.5pt Spread to receive say 0.25 pit (10% min premium) is about KRW 125,000 (~USD 115.75), I will need to tie up USD 637/510 initial/maintenance margin.  Return On Margin (ROM) is 18.17%/22.69%.

4. Option price spread and volume
K200 Option spread is generally about 2 ticks wide.  Selling at midpoint has been generally successful.  The Bid and Ask volume is also good.

However, HSI Option spread is about 4 ticks wide.  Selling at midpoint has been not successful.  The Bid and Ask volume is also comparatively lower.


Risk/Reward
1. Spread Risk
- min spread is 200 points, which equate to HKD 10,000.00 (~USD 1,288.94)
- K200 min spead is 2.5 points, which equate to KRW 1,250,000 (~USD 1,165.39)
- this is about the same

2.  Support & Resistance
- as my selection of Strike is primary base on Support & Resistance, the validity of Support & Resistance is important
- HSI gaps up & down very often.  This make the Support & Resistance not so reliable.  Very unpredictable.  This inherently results in higher risk.
- In addition, the up & down swing could be 300-500, even 700 points in one day!


Conclusion
HSI Option is not easy to trade as there are too many gaps up & down.  And the up & down swing is huge.  This make selection of Strike extremely difficult.  It is thus more risky.  The short strike could be hit easily.  In addition, for the same USD 100 premium received, I will need almost twice the margin as compared to K200.  Not to mentioned, the commission and market data fee is higher.
Therefore, HSI Option is not a suitable market/product for me to trade (at least for now).  I will need to expore some more market/product, such as Japan or Europe Options.

Friday, January 10, 2014

K200 Jan 09 Expiration

These are my trades for K200 09Jan14 contract.

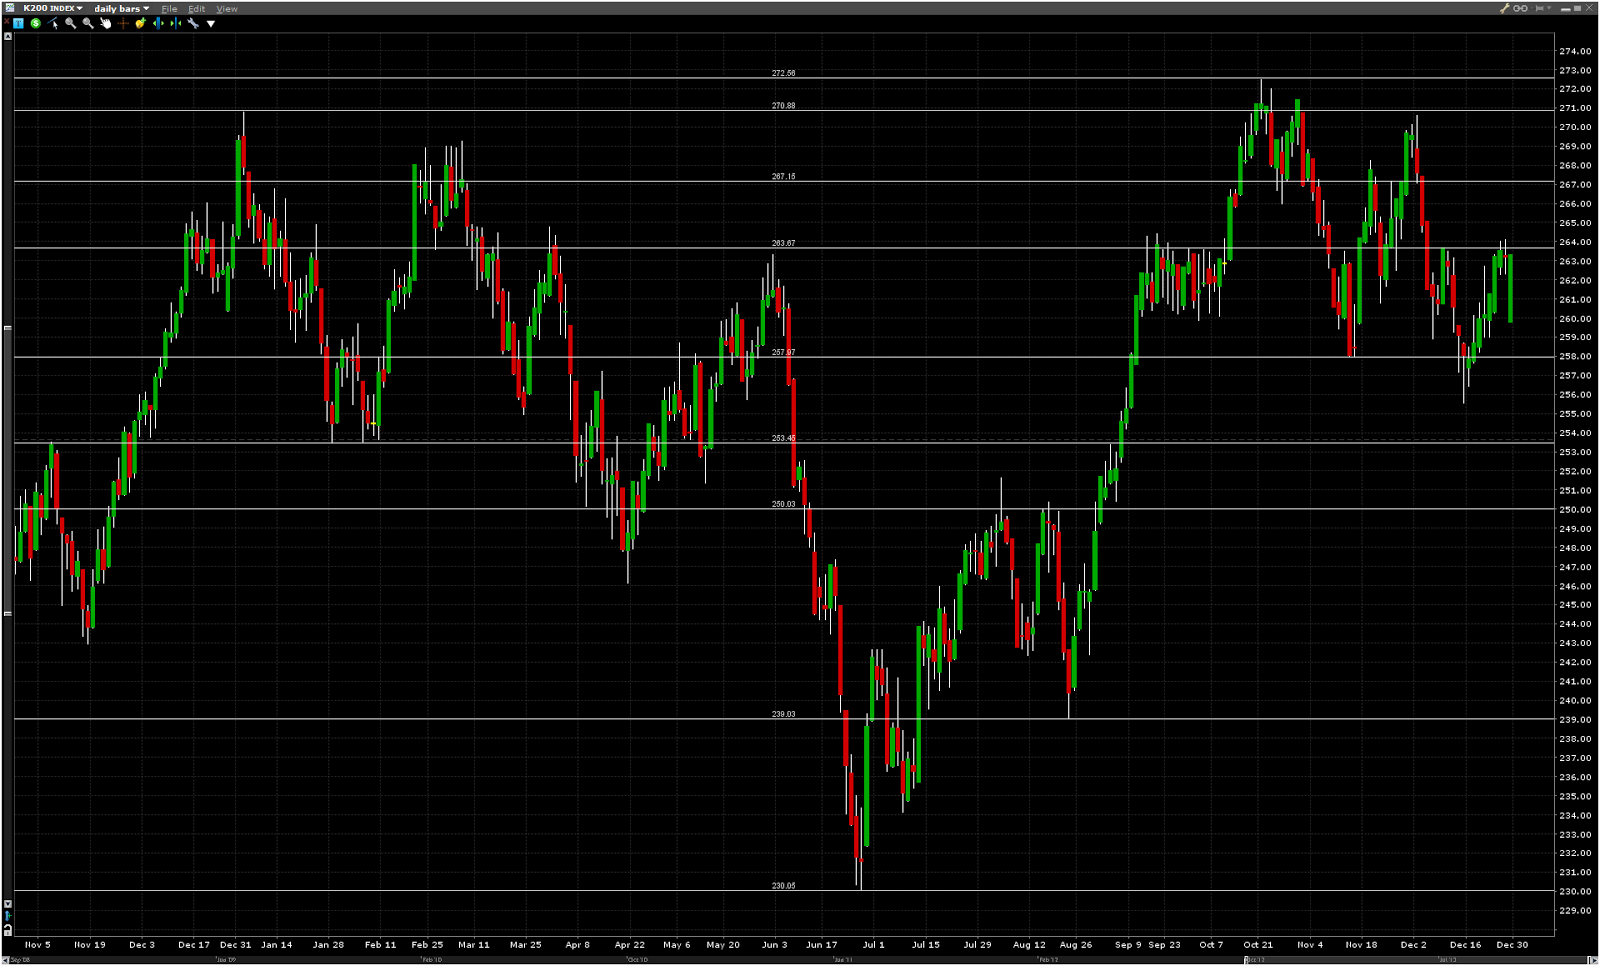
The below chart is K200 Index Daily Chart as at 02-Dec.  Since the K200 was still climbing up with a higher high higher low, my view was still bullish.  However, I was not comfortable with the last swing low at 258.  I wanted a safer Strike lower.  Thus I picked the last resistance at 250.


I sold 5 contracts of K200 Vertical Spread 09Jan14 250.0/247.5 Put, receiving KRW 650,000.00 (before commission)


The below daily chart is as at 17-Dec.  When K200 hit pass the last swing low of 258, I wasn't too sure about my bullish view.  It is showing a lower high lower low now.


I wanted to perform adjustment to my position, however I am not too sure what to adjust.  Should I cut loss now but it still has 8 points before hitting my Short Strike at 250?  Should I roll?  This topic of adjustment is an important knowledge I need to acquire in the near future.  Anyhow, I did something.

The below Weekly chart is as at 13-Dec.  We can see that K200 is within the trading range of 230-272.50 for the last two years (2012-2013).  There is no Strike price for me to sell 230/227.5 Put Spread.  I decided to sell 272.5/270.0 Call Spread instead.  I wasn't aware that my position became Iron Condor when I sold the Call Spread.  Anyhow, this Iron Condor was in line with my Weekly trading range view.


This is the trade report for 272.5/275.0 Call Spread, which bring in KRW 275,000.00 (before commission).


The below daily chart is as at 27-Dec.  When I saw that K200 failed to break the resistance near 264, I am more convinced with my new bearish view.  I decided to sell another Call Spread.  And I don't think it even can go up beyond the last swing high at 270.


Thus, I took a trade of  Call Spread 270.0/272.5, with a credit of KRW 675,000.00 (before commission).  I wasn't aware that this 2.5pt Call Spread of 270.0/272.5 had combine with the previous 2.5pt Call Spread of 272.5/275.0 into a 5pt Call Spread of 270.0/275.0.  At the same time, it had make a realized profit of KRW 122,850.00 (USD 116.37) after commission.


The below daily chart as at 03-Jan 9.22am confirmed my bearish view.  K200 continued the big drop on 02-Jan and hit pass the last swing low of 255.5.  However, we were just 5 working days (including 03-Jan) away, I didn't think K200 will drop below 250 and 245.  Taking advantage of the high volatility in Put Options, I sold another 5 contracts of 250.0/247.5 Put Spread and 10 contracts of 245.0/242.5 Put Spread.


The additional 5 contracts of 250.0/247.5 Put Spread brought in additional KRW 550,000.00 (before commission) and the 10 contracts of 245.0/242.5 Put Spread brought in KRW 400,000.00 (before commission), totaled KRW 950,000.00 (before commission).


This is at Expiration on 9-Jan.  K200 closed at 253.63.


All contracts expired worthless.  I got to keep the full KRW 2,406,450.00 (USD 2,263.82) premium (after commission/fee) as profit.  With the realized profit, KRW 122,850.00 (USD 116.37), on 30-Dec, that will be KRW 2,529,300.00 (USD 2,380.19) for January.


Monday, December 23, 2013

Last trade in December

My last live trade in December.

As you can see from the chart as at 30-Nov, it is clearly a uptrend.  A good last swing low will be at about 1650.  But the premium is too low to sell the credit put spread.  After going through different strikes, I selected 1760/1750 put spread, with USD 625 (after commission 596.60) premium.


This is the Order Preview.  Initial/Maintenance Margin is 4,388/3,511.  Return On Margin (ROM) is 14.24%/17.80% (13.59%/16.99% after comission) for 20 days.


This is the trade transaction.


This is the chart as at 20-Dec.  ES once droped to a low of 1760.25, just 1 tick above my Short Strike.  With Bernanke's tapering announcement of reducing bond buying by $10 billion a month and keeping interest rate as it is (not raising the interest rates until 2015 at the earliest), ES rallied to close at 1810.75.  The next two days ES Dec future contract stayed about the same level and end at 1812.89.
Thus, the option expired worthless.


This the trade for expiration (no commission).


With this, my total December income is USD 1,610.09 (596.60+1,013.49 posted here), met my monthly income goal as described in my Trading Plan.  This Trading Plan is still work in progress.  I will update it as I learn through reading, trading.

Sunday, December 22, 2013

Weekly Review

Trade 1 : Selling ASML Vertical Spread DEC2013 87.5/85 Put

ASML was hovering around the last week close 88.10 for a few days before it went up, maybe due to the tapering announcement.  It close at 91.48, above both of our strike price.  The option expired worthless.


This is the closing trade with 174.82 profit.


This trade is an evidence of the benefit of selling that i described in this Selling Options post.

For Options seller, say Put Options, we just need to be right that price didn't drop a lot.  We will make a profit 4 out of 5 scenario below:

1. Stay flat (win)
2. Rise a little (win)
3. Rise a lot (win)
4. Drop a little (win)
5. Drop a lot (loss)


I was bullish on this stock when it had a pin bar at the last resistance turned support.  And it was on its uptrend.  However, it didn't went up as expected.  It closed with a drop a little that still result in a winning trade.

Going forward, I will blog on live trade instead of demo trade.  This will be the last post on demo trade.