Friday, January 24, 2014

HSI Index Option Review

I want to trade another market/product in addition to K200 Index Option to diversify.  With that, I start to explore Hong Kong Hang Seng Index Option.

Basic Option Spec: (http://www.hkex.com.hk/eng/prod/drprod/hkifo/options.htm)

  • Exercise Style : European
  • HSI Option is HKD 50 per index point
  • Minimum Spread : 200 point, ie HKD 10,000 (~USD  1,288.94)
  • Trading Hours is 9:15m - 12:00noon & 1:00pm - 4.15pm


Cost of Trading
1. Market Data HKD 40.00 HKD (~USD 5.16)
- Hang Seng Indices HKD 15.00
- HKFE Deriv HKD 25.00
- Korean Stk Exch Deriv Free

IB market data is generally cheap.  While USD 5.16 market data per month is not expensive, it is relative more expensive than other exchanges.  For example, Korea is free, Singapore is SGD 1.00 (~USD0.78) and US Bundle (USD 10.00)  & US Options (USD 1.50) are waived when monthly commission generated reached USD 30.00 & USD 20.00 respectively.

2. Commission
- HKD 30.00 (~USD3.86) per contract
- 0.2% of option value, min KRW 1,000 (~USD 0.93) per order

For a 10% premium collected from Credit Spread,
- HSI commission will take 6% away from the 10% premium received, ie for every $100 premium received, $6 will be deducted for commission.
- K200 commission will only take about 0.76% (depending on contract value) from the premium, ie for every $100 premium received, only about $0.76 is deducted for commission.

3. Margin
- for a HSI Option 200pt Spread (min spread), the Initial & Maintenance margin is about USD 1,201 & USD 961 respectively
- for a K200 Option 2.5pt Spread (min spread), the Initial & Maintenance margin is about USD 637 & USD 510 respectively

For HSI Option, selling a 200pt Spread to receive say 20 pt (10% min premium) is about HKD 1,000 (~USD 128.81), I will need to tied up USD 1,201/961 initial/maintenance margin.  Return On Margin (ROM) is 10.72%/13.40%.

For K200 Option, selling a 2.5pt Spread to receive say 0.25 pit (10% min premium) is about KRW 125,000 (~USD 115.75), I will need to tie up USD 637/510 initial/maintenance margin.  Return On Margin (ROM) is 18.17%/22.69%.

4. Option price spread and volume
K200 Option spread is generally about 2 ticks wide.  Selling at midpoint has been generally successful.  The Bid and Ask volume is also good.

However, HSI Option spread is about 4 ticks wide.  Selling at midpoint has been not successful.  The Bid and Ask volume is also comparatively lower.


Risk/Reward
1. Spread Risk
- min spread is 200 points, which equate to HKD 10,000.00 (~USD 1,288.94)
- K200 min spead is 2.5 points, which equate to KRW 1,250,000 (~USD 1,165.39)
- this is about the same

2.  Support & Resistance
- as my selection of Strike is primary base on Support & Resistance, the validity of Support & Resistance is important
- HSI gaps up & down very often.  This make the Support & Resistance not so reliable.  Very unpredictable.  This inherently results in higher risk.
- In addition, the up & down swing could be 300-500, even 700 points in one day!


Conclusion
HSI Option is not easy to trade as there are too many gaps up & down.  And the up & down swing is huge.  This make selection of Strike extremely difficult.  It is thus more risky.  The short strike could be hit easily.  In addition, for the same USD 100 premium received, I will need almost twice the margin as compared to K200.  Not to mentioned, the commission and market data fee is higher.
Therefore, HSI Option is not a suitable market/product for me to trade (at least for now).  I will need to expore some more market/product, such as Japan or Europe Options.

Friday, January 10, 2014

K200 Jan 09 Expiration

These are my trades for K200 09Jan14 contract.

The below chart is K200 Index Daily Chart as at 02-Dec.  Since the K200 was still climbing up with a higher high higher low, my view was still bullish.  However, I was not comfortable with the last swing low at 258.  I wanted a safer Strike lower.  Thus I picked the last resistance at 250.


I sold 5 contracts of K200 Vertical Spread 09Jan14 250.0/247.5 Put, receiving KRW 650,000.00 (before commission)


The below daily chart is as at 17-Dec.  When K200 hit pass the last swing low of 258, I wasn't too sure about my bullish view.  It is showing a lower high lower low now.


I wanted to perform adjustment to my position, however I am not too sure what to adjust.  Should I cut loss now but it still has 8 points before hitting my Short Strike at 250?  Should I roll?  This topic of adjustment is an important knowledge I need to acquire in the near future.  Anyhow, I did something.

The below Weekly chart is as at 13-Dec.  We can see that K200 is within the trading range of 230-272.50 for the last two years (2012-2013).  There is no Strike price for me to sell 230/227.5 Put Spread.  I decided to sell 272.5/270.0 Call Spread instead.  I wasn't aware that my position became Iron Condor when I sold the Call Spread.  Anyhow, this Iron Condor was in line with my Weekly trading range view.


This is the trade report for 272.5/275.0 Call Spread, which bring in KRW 275,000.00 (before commission).


The below daily chart is as at 27-Dec.  When I saw that K200 failed to break the resistance near 264, I am more convinced with my new bearish view.  I decided to sell another Call Spread.  And I don't think it even can go up beyond the last swing high at 270.


Thus, I took a trade of  Call Spread 270.0/272.5, with a credit of KRW 675,000.00 (before commission).  I wasn't aware that this 2.5pt Call Spread of 270.0/272.5 had combine with the previous 2.5pt Call Spread of 272.5/275.0 into a 5pt Call Spread of 270.0/275.0.  At the same time, it had make a realized profit of KRW 122,850.00 (USD 116.37) after commission.


The below daily chart as at 03-Jan 9.22am confirmed my bearish view.  K200 continued the big drop on 02-Jan and hit pass the last swing low of 255.5.  However, we were just 5 working days (including 03-Jan) away, I didn't think K200 will drop below 250 and 245.  Taking advantage of the high volatility in Put Options, I sold another 5 contracts of 250.0/247.5 Put Spread and 10 contracts of 245.0/242.5 Put Spread.


The additional 5 contracts of 250.0/247.5 Put Spread brought in additional KRW 550,000.00 (before commission) and the 10 contracts of 245.0/242.5 Put Spread brought in KRW 400,000.00 (before commission), totaled KRW 950,000.00 (before commission).


This is at Expiration on 9-Jan.  K200 closed at 253.63.


All contracts expired worthless.  I got to keep the full KRW 2,406,450.00 (USD 2,263.82) premium (after commission/fee) as profit.  With the realized profit, KRW 122,850.00 (USD 116.37), on 30-Dec, that will be KRW 2,529,300.00 (USD 2,380.19) for January.


Monday, December 23, 2013

Last trade in December

My last live trade in December.

As you can see from the chart as at 30-Nov, it is clearly a uptrend.  A good last swing low will be at about 1650.  But the premium is too low to sell the credit put spread.  After going through different strikes, I selected 1760/1750 put spread, with USD 625 (after commission 596.60) premium.


This is the Order Preview.  Initial/Maintenance Margin is 4,388/3,511.  Return On Margin (ROM) is 14.24%/17.80% (13.59%/16.99% after comission) for 20 days.


This is the trade transaction.


This is the chart as at 20-Dec.  ES once droped to a low of 1760.25, just 1 tick above my Short Strike.  With Bernanke's tapering announcement of reducing bond buying by $10 billion a month and keeping interest rate as it is (not raising the interest rates until 2015 at the earliest), ES rallied to close at 1810.75.  The next two days ES Dec future contract stayed about the same level and end at 1812.89.
Thus, the option expired worthless.


This the trade for expiration (no commission).


With this, my total December income is USD 1,610.09 (596.60+1,013.49 posted here), met my monthly income goal as described in my Trading Plan.  This Trading Plan is still work in progress.  I will update it as I learn through reading, trading.

Sunday, December 22, 2013

Weekly Review

Trade 1 : Selling ASML Vertical Spread DEC2013 87.5/85 Put

ASML was hovering around the last week close 88.10 for a few days before it went up, maybe due to the tapering announcement.  It close at 91.48, above both of our strike price.  The option expired worthless.


This is the closing trade with 174.82 profit.


This trade is an evidence of the benefit of selling that i described in this Selling Options post.

For Options seller, say Put Options, we just need to be right that price didn't drop a lot.  We will make a profit 4 out of 5 scenario below:

1. Stay flat (win)
2. Rise a little (win)
3. Rise a lot (win)
4. Drop a little (win)
5. Drop a lot (loss)


I was bullish on this stock when it had a pin bar at the last resistance turned support.  And it was on its uptrend.  However, it didn't went up as expected.  It closed with a drop a little that still result in a winning trade.

Going forward, I will blog on live trade instead of demo trade.  This will be the last post on demo trade.

Sunday, December 15, 2013

Second set of Live Trades

This is my second set of Live Trades, on Korea KOSPI 200 Index Option (K200).

After my first live trade on ES, I wanted some Options that are active during my day time (Singapore time).  And I ended trading KOSPI 200 Index Option.
(I will have another post explaining the various Asia Pacific exchanges Index Options or Futures Options that I explore.)

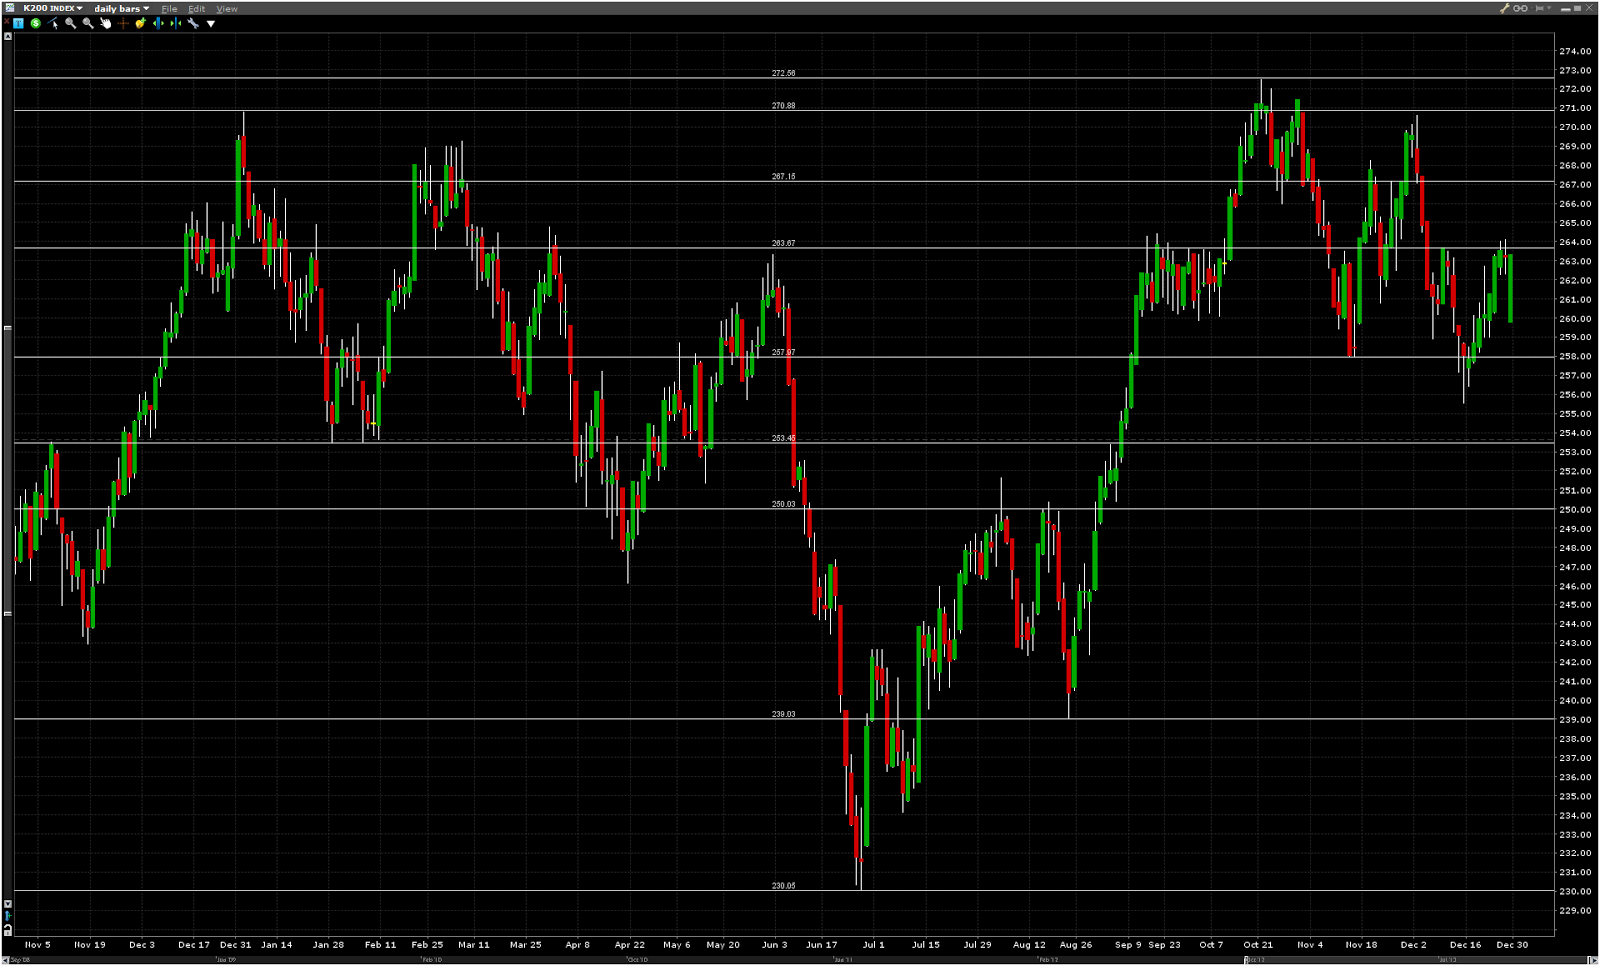
The below chart is K200 Index Daily chart as at 25-Nov.  I saw that K200 Index has been on uptrend since July.  October retracement stopped at about 258 before climbing up again.  I want a Strike price at July swing low of 230 or August swing low of 240 as the support.  But the premium for Put Option is so low that I cannot even create a Vertical Spread.

So, I chosen the nearest swing low on November of 258 as the support, which I was a bit worry (will elaborate more in subsequent post).  And I also enter a trade at the the last resistance in August of 250, hoping that the resistance will become a support.


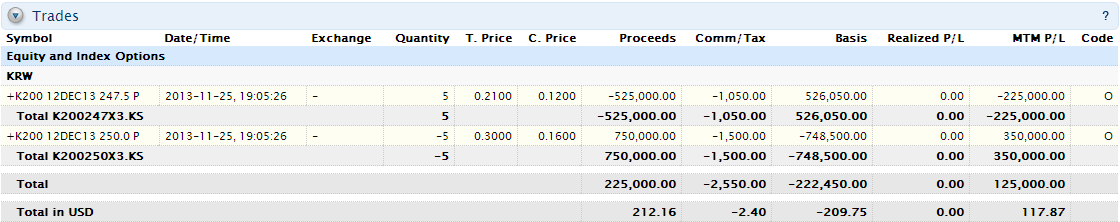
I did two trades on K200 Index Option on two separate days:
25-Nov :  Sell 5 contracts of K200 Vertical Spread DEC12'13 257.5/255.0 Put
26-Nov : Sell 5 contracts of K200 Vertical Spread DEC12'13 250.0/247.5 Put

Order preview for K200 Vertical Spread DEC12'13 257.5/255.0 Put.  I forgot to create the image for Order preview for the 250.0/247.5 Put spread.


The below are the trades report.  As can be seen, the premium for 257.5/255.0 spread is KRW 450,000.00 (before commission), double of the 250.0/247.5 spread of KRW 225,000.00 (before commission).


I added another two contract of 257.5/255.0 on 6-Dec.  As you can see, the last few days drop paused at the shaded region where price was stalled in the last climb.  I expect the price to hold.  It seems to hold.  And the premium was attractive.  With just 2 contracts, the premium (KRW 400,000.00) collected is about the same as the 5 contracts I sold on 25-Nov (KRW 450,000.00).


This is at Expiration on 12-Dec.  K200 Index close at 259.05, touching low at 257.20.  All contracts expired worthless.  So, I got to keep the full KRW 1,065,690 (which is USD 1,013.49) premium (after commision/fee) as profit.


Saturday, December 14, 2013

Weekly Review

Trade 1 : Selling ASML Vertical Spread DEC2013 87.5/85 Put

ASML drop down to 88.10, just 0.60 above our higher strike price of 87.5.  This is not looking good.  With another week to go, will ASML hold above 87.5?  The spread was sold for 0.35.  So, the Break Even point is 87.15 (87.5 - 0.35).  If ASML goes below 87.15, I will start to incur loss.


The Loss is now $130.


It was said that Delta is another way of looking at the probability that the option will go ITM (In The Money).  Delta for 87.5 Put is currently at 0.4135, which means 41.35% of getting ITM.  This is very bad.


Can I roll?  Should I roll?  Rolling is a concept that I still have not grasp.  To me, it is no difference of closing the current position and open a new position.  Anyhow, I will cover/explore this in another post.


Friday, December 13, 2013

Karen SuperTrader - Made $41 Million Profit in 3 Years Option Trading

Saw these two YouTube videos from tastytrade.  Inspiring for retail trader, for me at least.

Video1


Video2